Student Loans and Financial Aid
Quality reviewed September 2026
- Grades
- Grades 9-12
- Time
- About two 50-minute class periods
- Includes
- 11 ready-to-teach files
- Format
- Word (.docx) · PowerPoint (.pptx)
- Slide deck
- Guided notes
- Guided notes teacher key
- Activity + answer key
- Quiz + answer key
- Exit ticket + answer key
- Teacher guide
- Teacher presentation notes
What students do
- Calculate total repayment cost on a loan using the simple-interest formula
- Compare federal and private student loans across rate, protections, and forgiveness
- Map three graduates' loan situations and explain who pays the most and least
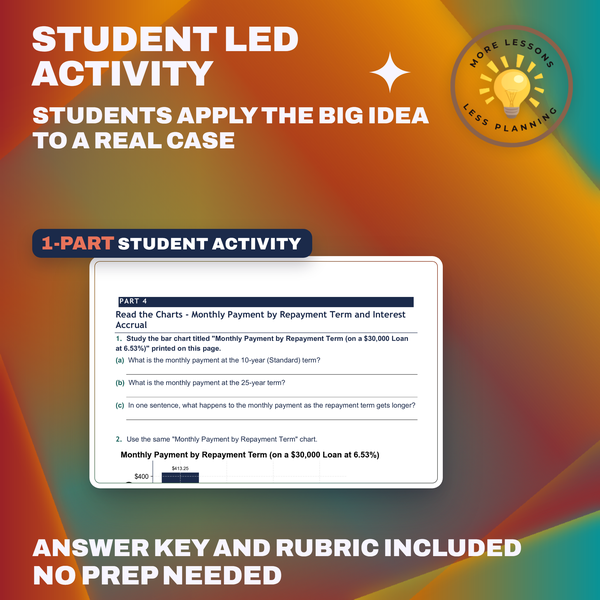
- Read charts on interest accrual during school and monthly payment by repayment term
What it covers
- Grants and scholarships, federal loans, and private loans, and the order to use them in
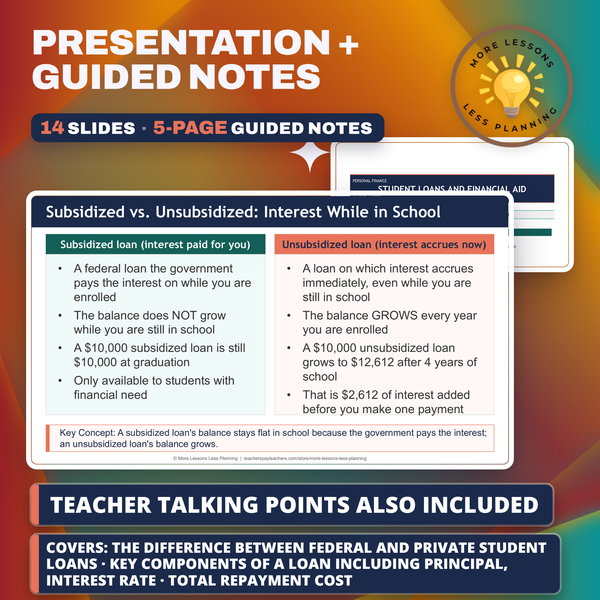
- Subsidized vs unsubsidized loans and what happens to the balance while you're still enrolled
- Standard vs income-driven repayment and the tradeoff between monthly payment and total interest
- The FAFSA process and why filing early matters
Learning targets
- Explain the difference between federal and private student loans
- Identify key components of a loan including principal, interest rate, and term
- Calculate total repayment cost using the simple-interest formula
- Compare repayment plan options and their long-term financial impact
- Evaluate whether borrowing for education is worth the investment
Peek inside
Three Ways to Pay - In Order
Grants and scholarships are money that does not need to be repaid, awarded for financial need, merit, or both.
A Pell Grant from the FAFSA covers up to $ per year toward college costs.
Federal Before Private
Each year, sets the fixed interest rates on federal student loans borrowed from the U.S. government.
You should always exhaust grants, scholarships, and loans before considering private loans.
1. Q1. The original amount of money you borrow, before any interest is added, is the of the loan.
Why this matters
Maria, James, and Aisha borrow for the same degree, yet their loan files land nowhere near each other, from James's $60,000 after community college to Aisha's $200,000, part of it private at 9.50 percent. That spread has less to do with luck than with decisions made years before a diploma, decisions most students have never watched anyone walk through.
I hand students three real files instead of one because the order of grants, scholarships, federal loans, and private loans only makes sense once you see what happens when someone skips a step. Working as the financial aid counselor on all three cases makes filing the FAFSA early and exhausting federal loans first feel like more than advice, it is the real difference between James's number and Aisha's.
From one teacher to another
Three loan files land on students' desks at once: Maria's $120,000 at a state university, James's $60,000 after starting at community college, and Aisha's $200,000 with $35,000 of that borrowed privately at 9.50%. Working as the financial aid counselor, they run the same simple-interest formula across all three and watch identical loan amounts land on wildly different total costs depending only on the repayment term. I don't have to tell them federal comes before private after that, the numbers already did it.
Every file in this toolkit
-
Activity (Student)
Maria, James, and Aisha each borrowed differently for college, so students run the simple-interest formula on all three loan files, then read a monthly-payment chart beside a subsidized-versus-unsubsidized balance chart before ranking who pays the least interest.
-
Activity (Answer Key)
James pays the least in total interest at $9,795 by starting at community college, while Aisha's $48,269 total is driven mostly by a single $35,000 private loan that alone costs $33,250, more than her two federal loans combined.
-
Exit Ticket (Student)
What actually sets an income-driven monthly payment gets tested first, beside a strategy that will not speed up payoff and a $25,000 loan compared at 6 percent across a 10-year and a 20-year term. The write asks for one advantage and one disadvantage, tied to the monthly payment and total interest.
-
Exit Ticket (Answer Key)
Naming a lower monthly payment as the advantage and a 20-to-25-year term as the disadvantage earns full credit across four rubric points scoring the income-driven repayment answer.
-
Guided Notes (Student)
Notes trace the $7,395 Pell Grant cap, the FAFSA's October 1st opening date, and simple interest across nine sections, ending on a $30,000 loan worked out at 6.53 percent over 10 and 20 years.
-
Guided Notes (Teacher Key)
$19,590 is the extra interest owed once a $30,000 loan stretches from 10 to 20 years, alongside the October 1st FAFSA date, the $7,395 Pell Grant cap, and the $37,574 average graduate balance.
-
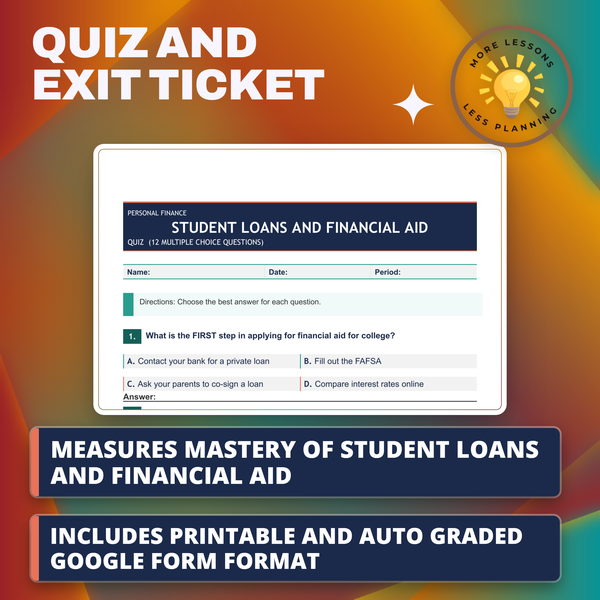
Quiz (Student)
Filing the FAFSA first opens this set, which also tests subsidized-versus-unsubsidized interest accrual, a $20,000 loan at 5% simple interest, Parent PLUS eligibility, and what APR actually covers.
-
Quiz (Answer Key)
FAFSA-first is marked as the correct opening step, next to the $20,000-at-5%-interest calculation and which federal loan type actually requires a parent to co-apply for approval.
-
Slides
The average graduate owes $37,574 against a $1.77 trillion national total, and these slides work back from that figure to the order that keeps a bill smaller: grants and federal loans first, and a subsidized loan that stays flat in school while an unsubsidized one grows to $12,612.
-
Teacher Guide
James repays only $24,795 by choosing a community-college start, while Maria's state-university path costs $36,366, the comparison this guide's Activity runs on. Extensions research a real school's cost, run a subsidized-versus-unsubsidized face-off, and test James's savings against fresh numbers.
-
Teacher Presentation Notes
U.S. student debt has passed $1.77 trillion and the average graduate owes $37,574, the scale behind a $30,000 loan at 6.53% growing to $49,590 over ten years or $69,180 stretched across twenty.
Download
Where should I send the next one?
Everything here is free and it stays that way. Leave your email and I'll send you the new lessons as they go up. You can unsubscribe from any one of them.
Related resources
Cosigning and Co-Borrowing - Sharing the Risk
Interest Explained - Simple vs Compound
Loan Default - What Happens When You Can't Pay
Payday Loans - The 400 Percent APR Trap
The Debt Snowball vs Avalanche - Paying It Off
What Is a Loan? Principal, Interest & Terms
Every lesson on this site is free to download and use. If one of them saved you a prep period, you can chip in a few bucks toward my three kids' daycare fund. That's genuinely where tips go.