Renters and Homeowners Insurance - Protecting Your Stuff
Quality reviewed September 2026
- Grades
- Grades 9-12
- Time
- About two 50-minute class periods
- Includes
- 11 ready-to-teach files
- Format
- Word (.docx) · PowerPoint (.pptx)
- Slide deck
- Guided notes
- Guided notes teacher key
- Activity + answer key
- Quiz + answer key
- Exit ticket + answer key
- Teacher guide
- Teacher presentation notes
What students do
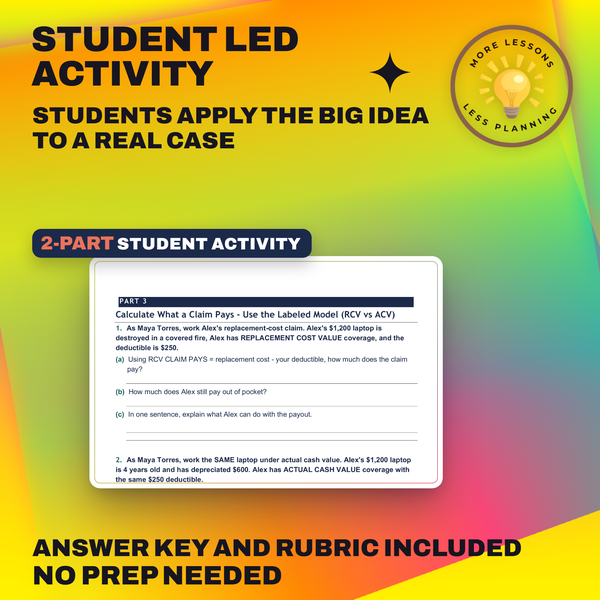
- Calculate what a $1,200 laptop claim pays under replacement cost value versus actual cash value
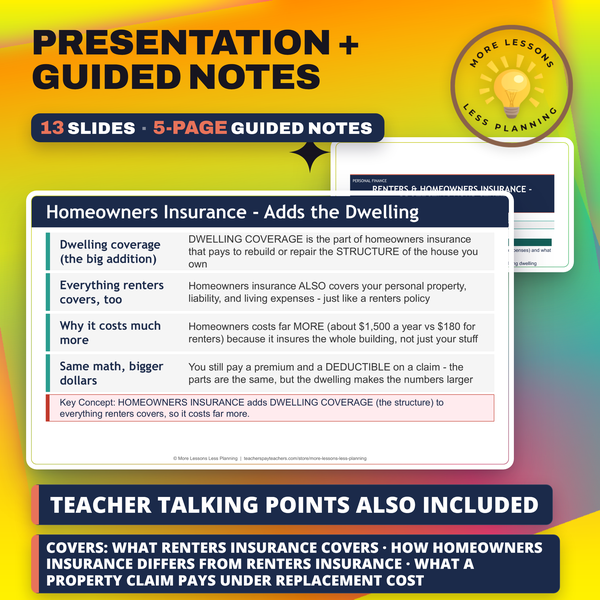
- Compare what renters insurance covers against what homeowners insurance adds
- Read a bar chart weighing a year of renters insurance against the cost of replacing a first apartment's belongings
- Advise a first-time renter on choosing coverage and a deductible they could actually afford
What it covers
- What renters insurance pays for and what it excludes, from personal property to the building itself
- How homeowners insurance adds dwelling coverage for the structure
- The math behind replacement cost value versus actual cash value on a claim
Learning targets
- Explain what renters insurance covers (personal property, liability, living expenses) and what it does not cover (the building, floods)
- Explain how homeowners insurance differs from renters insurance by adding dwelling coverage for the structure
- Calculate what a property claim pays under replacement cost value (RCV) versus actual cash value (ACV) using a labeled model
- Explain why renters insurance is inexpensive relative to the cost of replacing your belongings out of pocket
Peek inside
✔
Two policies for where you live
RENTERS INSURANCE is for people who RENT; HOMEOWNERS INSURANCE is for people who OWN their home
✔
Renters covers your belongings
Two Policies for Where You Live
RENTERS INSURANCE (insurance that covers a renter's belongings and liability, not the building) is for people who .
HOMEOWNERS INSURANCE (insurance that covers the dwelling plus belongings and liability for an owner) is for people who their home.
Who Insures What
Renters insurance covers your PERSONAL PROPERTY (your belongings - furniture, electronics, clothing) but NOT the .
When you rent, the LANDLORD's own policy covers the structure; homeowners insurance covers your belongings AND the DWELLING because you the home.
1. The insurance that covers a renter's belongings and liability, but not the building, is .
Why this matters
Replacement cost value and actual cash value sound like interchangeable jargon until a $1,200 laptop claim pays out two different amounts under each one. Students run that claim twice, so the gap between payouts stops being abstract and becomes real money, then use that lens to sort what renters insurance covers from what homeowners insurance adds.
I teach renters insurance before homeowners on purpose, since almost none of my students will own a house before they rent an apartment, and treating it as homeowners' smaller sibling undersells it. By the end they can look around their own room and tell you exactly what a real claim would pay for.
From one teacher to another
Almost none of my students will own a house before they rent an apartment, so I teach renters insurance first and don't treat it like homeowners' little sibling. They run the same laptop claim twice, once under replacement cost value and once under actual cash value, until the gap between those two payouts stops being abstract. By the end they can look at everything they own and tell you exactly what a real claim would pay for it.
Every file in this toolkit
-
Activity (Student)
Alex's $1,200 laptop burns in a covered fire, and Maya Torres has students price the same claim twice, once under replacement cost value and once under actual cash value, before pricing what a renters premium actually costs.
-
Activity (Answer Key)
Alex's $1,200 laptop claim pays $950 under replacement cost coverage but only $350 under actual cash value, a $600 gap that mirrors the chart's own numbers, $180 for a year of renters insurance against $7,000 to replace everything from scratch.
-
Exit Ticket (Student)
What a renter's own policy actually covers gets tested first, then a $1,200 laptop claim runs through a $250 deductible under replacement cost value, and homeowners coverage gets compared for what it adds on top. Personal property, deductible, and replacement cost value get worked in.
-
Exit Ticket (Answer Key)
Naming personal property coverage, the building exclusion, and the $950 payout on a $1,200 laptop claim each earn a rubric point, which also grades the three answer choices on what a landlord covers versus a renter's own policy.
-
Guided Notes (Student)
A $1,200 laptop claim runs through this page twice, once paying out under replacement cost value and once under actual cash value, landing on the dollar gap between a $950 and a $350 payout.
-
Guided Notes (Teacher Key)
$950 under replacement cost value and $350 under actual cash value are the two payouts on the same $1,200 laptop, plus the landlord-versus-dwelling coverage split spelled out in full.
-
Quiz (Student)
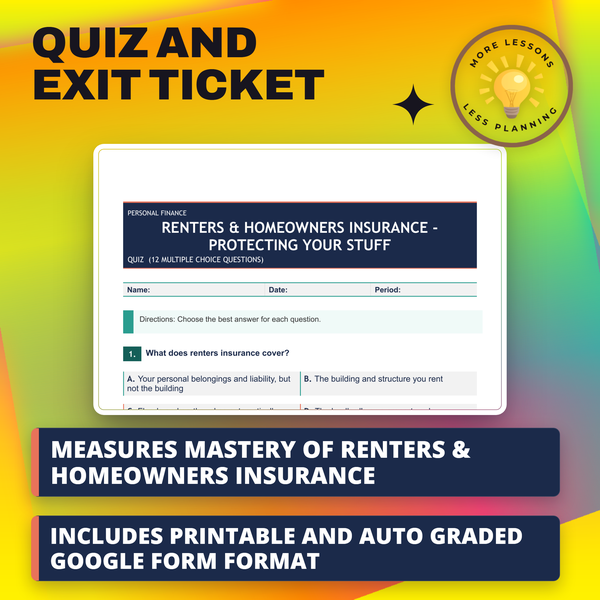
The coverage split between renters and homeowners insurance drives several questions, next to a replacement-cost-value claim on a $1,200 laptop and why a higher deductible lowers a premium.
-
Quiz (Answer Key)
The landlord covering the building structure is the marked answer, and the $350 actual cash value payout on that laptop claim, once depreciation is subtracted, finishes the set.
-
Slides
A $1,200 laptop sits at the center of the labeled model comparing replacement cost and actual cash value, paying $950 one way and just $350 the other, while a separate slide sets renters insurance near $180 a year against homeowners near $1,500.
-
Teacher Guide
The same $1,200 laptop pays $950 under replacement cost value but only $350 under actual cash value, a $600 gap this 55-point guide teaches on one item. Extensions sort eight loss scenarios as covered or not, build a personal home inventory, and run an RCV-versus-ACV showdown on three more items.
-
Teacher Presentation Notes
One year of renters insurance runs $180 against $7,000 to replace everything a renter owns, the gap ahead of the replacement cost formula and why homeowners insurance costs more once it adds coverage for the dwelling itself.
Download
Where should I send the next one?
Everything here is free and it stays that way. Leave your email and I'll send you the new lessons as they go up. You can unsubscribe from any one of them.
Related resources
Choosing Coverage: How Much Do You Really Need?
Health Insurance - The Most Confusing Bill You'll Get
Life Insurance - Planning for the Worst
What Is Insurance - Paying to Protect Yourself
Why Young People Pay More (or Less) - Risk Pricing in Auto Insurance
Banking Basics: Checking, Savings, and Debit Cards Explained
Every lesson on this site is free to download and use. If one of them saved you a prep period, you can chip in a few bucks toward my three kids' daycare fund. That's genuinely where tips go.