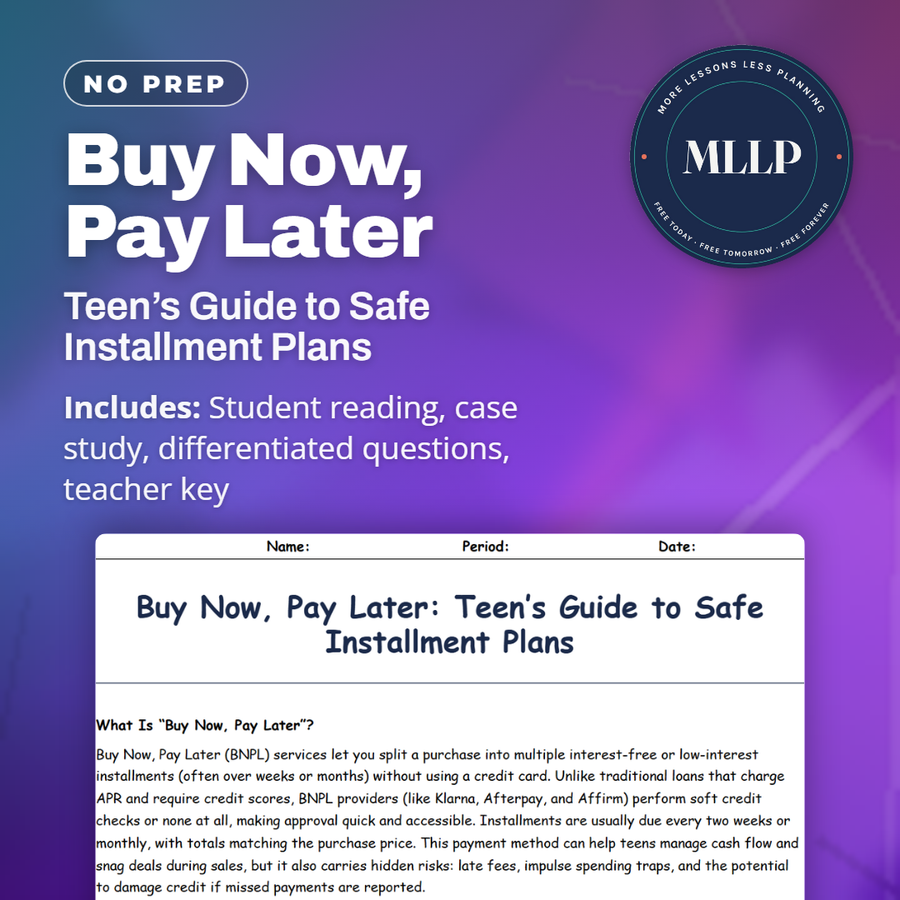
Buy Now, Pay Later: Teen’s Guide to Safe Installment Plans
Quality reviewed September 2026
Facts verified September 24, 2026
- Subject
- Career & Life Skills
- Grades
- Grades 9-12
- Length
- 7-page student worksheet
- Time
- About one 50-minute class period
- Great for
- Sub plans and independent work
- Includes
- Reading passage, comprehension questions + full answer key
- Format
- Print-and-go PDF
What students do
- Match five terms, deferred interest, soft credit check, installment schedule, late fee, and credit reporting, to their definitions
- Fill in the blanks on impulse purchases, late fees, and keeping a BNPL log
- Answer multiple choice questions on how BNPL differs from credit cards, what excessive use leads to, and what to check before picking a plan
- Write short answers on why overlapping plans raise financial risk, how reminders prevent late fees, and one benefit and one drawback of BNPL for teens
What it covers
- How Buy Now, Pay Later splits a purchase into installments through providers like Klarna, Afterpay, and Affirm
- A comparison table of fees, payment schedules, and late-fee policies across the three providers
- A case study on Carlos, who took on three overlapping BNPL plans worth $450 and missed two payments
Start reading this worksheet
What Is “Buy Now, Pay Later”?
Buy Now, Pay Later (BNPL) services let you split a purchase into multiple interest-free or low-interest installments (often over weeks or months) without using a credit card. Unlike traditional loans that charge APR and require credit scores, BNPL providers (like Klarna, Afterpay, and Affirm) perform soft credit checks or none at all, making approval quick and accessible. Installments are usually due every two weeks or monthly, with totals matching the purchase price. This payment method can help teens manage cash flow and snag deals during sales, but it also carries hidden risks: late fees, impulse spending traps, and the potential to damage credit if missed payments are reported.
Comparing Major Providers
Here’s how three leading BNPL services stack up: Teens should compare interest policies, payment cadence, and maximum fees before choosing. For small purchases under $200, 0% BNPL plans can be convenient; for larger buys, a short-term low-APR Affirm loan might cost more in interest but avoid repeated late fees.
Hidden Costs & Credit Impact
While many BNPL plans advertise “no interest,” missing a payment can trigger fees that effectively raise your cost. Multiple late fees can snowball, and in some cases, unpaid balances get sold to collections, hurting your credit score. Additionally, using BNPL excessively can encourage impulse buys: it feels like “free money” until you face a big bill. To protect your financial health: Read the Fine Print: Note any deferred interest clauses or minimum order amounts. Set Reminders: Calendar alerts before each installment due date. Limit Active Plans: Avoid more than two concurrent BNPL purchases. Check Reporting Policies: Confirm whether the provider reports to credit bureaus.
Like what you read? The full reading, the case study, and every question set are in the free download below, along with the answer key.
Why this matters
BNPL ads make splitting a purchase into four payments feel like free money, but the reading shows how fast that adds up once two or three plans overlap on the same paycheck. Students who shop online during sales, especially around back to school or the holidays, are exactly who these apps target, so knowing the difference between a soft credit check and a hard one, and what happens when a payment is missed, protects money they already worked for.
From one teacher to another
The first passage explains how BNPL services split a purchase into installments, often four payments every two weeks, without the credit checks a traditional loan requires. It compares Klarna, Afterpay, and Affirm side by side, showing that Klarna charges up to $7 per missed payment while Afterpay charges up to $10, and that Affirm instead runs interest of 0 to 30% APR depending on the merchant. From there it covers warning signs like deferred interest and credit reporting, then walks through a five-question checklist to run before checking out. Carlos ties it together: he took on three concurrent BNPL plans worth $450, missed a sneaker and a headphone installment when his work hours dropped, and had to ask Afterpay to waive a fee before limiting himself to one active plan at a time.
What you get
Download
Where should I send the next one?
Everything here is free and it stays that way. Leave your email and I'll send you the new lessons as they go up. You can unsubscribe from any one of them.
Related resources
Big Purchase Planning: Save for Gadgets & More
Credit Reports Uncovered: Monitor & Dispute Errors
Emergency Budget Blueprint: Teens’ Step-by-Step Guide
Finance Jargon Buster: Essential Terms for Teens
Hidden Bank Fees: Slash Your Sneaky Charges
Inflation Explained: Protect Teen Buying Power
Every lesson on this site is free to download and use. If one of them saved you a prep period, you can chip in a few bucks toward my three kids' daycare fund. That's genuinely where tips go.